The North American freight landscape is currently navigating a period of precarious stability. As of mid-September, the Outbound Tender Rejection Index (OTRI) remains fixed at approximately 13.5%, a figure that serves as a vital barometer for the health and tension of the domestic truckload market. While the post-Labor Day period typically signals a cooling of demand, current indicators suggest a more complex narrative—one defined by tight capacity, fluctuating fuel costs, and a high-stakes inventory environment as the industry barrels toward the critical fourth quarter.
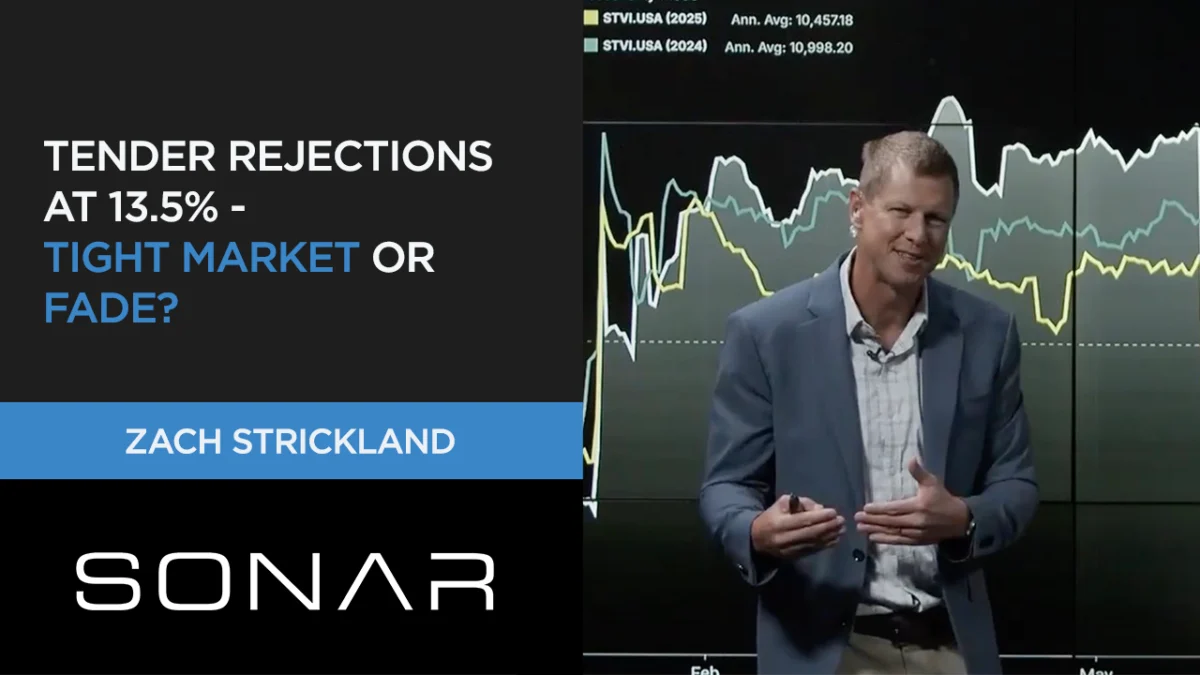
In his latest SONAR market update, freight market expert Zach Strickland highlighted that while rates may have retreated from their post-Labor Day peak, the structural tightness of the market persists. For carriers, brokers, and shippers alike, the current data suggests that the "easy" days of market predictability are over, replaced by a need for strategic agility.
The State of the Market: A Chronology of Post-Labor Day Volatility
The Labor Day holiday has historically functioned as a localized shock to the supply chain. However, this year, the disruption was notably more pronounced than at any point in the last three years. Following the holiday, the market experienced a significant surge in tender rejections—a clear signal that capacity, while available, is becoming increasingly selective.
September 10: The Baseline
As of September 10, the OTRI held steady at 13.45%. While this represents a slight cooling from the immediate post-holiday spike, it remains significantly elevated compared to historical norms for the same timeframe. This persistence suggests that the "tightness" observed throughout the summer was not merely a seasonal fluke, but a reflection of a supply chain operating near its functional capacity limits.
The Shift in Demand Dynamics
The Tender Volume Index (TVI), which provides a seven-day moving average of all accepted and rejected tenders, has exhibited a softening trend since mid-July. Analysts attribute this, in part, to a tactical shift in logistics strategy by major shippers. Faced with persistent rate volatility in the spot market, many shippers have aggressively converted long-haul dry van shipments to intermodal and rail. The East Coast rail network, in particular, has seen a marked increase in volume, absorbing loads that would have otherwise strained the truckload sector.
Supporting Data: Capacity, Fuel, and Inventory
To understand where the market is heading, one must look at the interconnected web of fuel surcharges, inventory risks, and import volumes.
The Fuel Factor
The National Truckload Index (NTI) for dry van spot rates currently sits at $3.43, a figure heavily influenced by the persistent rise in fuel costs. With retail diesel prices hovering near the $6-per-gallon mark, the economic burden on carriers is substantial. For shippers, this translates into rising fuel surcharges that show no sign of immediate relief. As these costs are passed down the supply chain, they exacerbate the pressure on operating margins, forcing both carriers and brokers to re-evaluate their contract commitments.
Lean Inventories and Q4 Urgency
Perhaps the most significant risk factor for the upcoming quarter is the state of national inventory levels. Current data indicates that inventories remain lean across the board. While this is often viewed as a positive for cash flow management, it presents a substantial risk heading into the holiday season.
If consumer demand remains unpredictable, shippers may be forced into "panic-buying" or expedited shipping scenarios. This is where the intermodal-to-truckload transition becomes critical. As the year progresses, intermodal capacity often becomes less fungible with trucking. Should shippers find themselves under-stocked during the holiday rush, the reliance on spot-market trucking could trigger another sharp rise in tender rejections, potentially mirroring or exceeding the volatility seen post-Labor Day.
Import Volumes and Regional Dispersion
Import data, tracked by the Inbound Ocean Tender Index (IOTI), remains elevated compared to earlier in the year and historical seasonal averages. This supports the conclusion that the supply chain is still working to restock, even if the final-mile demand remains soft.
However, looking at dry van spot rate maps, there is a marked geographic dispersion. Many lanes are currently running in "negative territory," indicating that capacity has not yet fully redistributed following the holiday surge. While this is typical of post-holiday seasonality, market experts anticipate a correction in the coming weeks as carriers move equipment back into high-demand corridors.
Official Perspectives: The Path Ahead
The consensus among industry analysts is that the market will remain tight for the duration of the year. The primary variable is no longer if the market will be tight, but the rate of change at which it will transition.
"It’s still going to be tight, I think, for the rest of the year," says Zach Strickland. "That’s not in question. It’s just the rate of change that we’re really interested in at this point."
For carriers, this means maintaining a disciplined approach to lane selection and focusing on yield management. For brokers, the challenge lies in managing shipper expectations while navigating the reality of carrier selectivity. For shippers, the mandate is clear: secure capacity early and consider the risks of relying on lean inventory models in an environment where expedited freight may be the only solution to meet holiday demand.
Strategic Implications for Stakeholders
For Carriers: Focus on Yield Over Volume
In a market where capacity is selective, carriers should prioritize lanes that offer consistent margins rather than chasing spot-market volume. The high fuel environment makes deadhead miles particularly punitive; therefore, optimizing route density and minimizing empty miles is essential for maintaining profitability in the final months of the year.
For Brokers: The Value of Transparency
Brokers are currently the "shock absorbers" of the supply chain. As tender rejections remain high, the ability to provide clear, data-backed communication to shippers regarding market conditions is a key competitive advantage. With the potential for a Q4 capacity crunch, building robust, reliable carrier networks now will be the difference between meeting delivery promises and facing service failures.
For Shippers: Preparing for Volatility
Shippers should be wary of the "efficiency trap." While keeping inventories lean has been a successful strategy for managing capital, the current market dynamics suggest that the risk of a supply chain disruption is rising. Shippers should evaluate their reliance on intermodal and develop contingency plans for truckload overflow. Engaging in proactive contract negotiations—rather than relying solely on the spot market—will be a necessary hedge against potential Q4 volatility.
Looking Toward the Future: The FreightTech Horizon
As the industry navigates these immediate challenges, the broader focus remains on the evolution of technology in freight. The upcoming Future of Freight Festival (F3), scheduled for late October in Chattanooga, serves as a focal point for the industry to address these issues collectively.
From the Brokerage Compliance Symposium, which will tackle critical issues such as fraud, cargo theft, and insurance liability, to the F3 Awards Dinner, where the industry’s most innovative "Shippers of Choice" will be honored, the event underscores the importance of collaboration. In an environment defined by high rejection rates and complex economic pressures, the winners of the coming year will be those who leverage data, embrace compliance, and foster deep, strategic partnerships across the supply chain.
Conclusion
The truckload market stands at a crossroads. While the immediate post-Labor Day volatility is beginning to settle, the underlying metrics—high tender rejections, rising fuel costs, and lean inventories—point toward a Q4 that could be defined by scarcity and urgency. Whether the market experiences a controlled glide path or a period of renewed disruption will depend largely on how shippers manage their inventory risks and how effectively carriers can navigate the tightening capacity landscape.
For now, the data remains the most reliable compass. As we head into the final quarter, the industry must remain vigilant, prioritize data-driven decision-making, and prepare for the potential of another significant shift in market dynamics as the holiday season approaches.
About the Author