The promise of artificial intelligence has triggered a gold rush of unprecedented proportions. As tech giants and specialized infrastructure developers race to secure the compute capacity necessary to train the next generation of large language models, the data center industry has become the primary theater of this high-stakes competition. However, beneath the surface of multi-billion-dollar announcements and ambitious development timelines, a sobering reality is emerging: the “data center boom” is hitting a wall of logistical, political, and physical constraints.
In this shifting landscape, the most critical question facing investors, policymakers, and industry observers is no longer how many data centers can be built, but rather, which ones will ever actually break ground.
The Reality Check: Why Projects Are Stalling
The narrative surrounding AI infrastructure often assumes a linear progression from announcement to ribbon-cutting. In reality, the path is fraught with obstacles that have begun to cull the herd of speculative projects.
Local Resistance and Regulatory Pushback
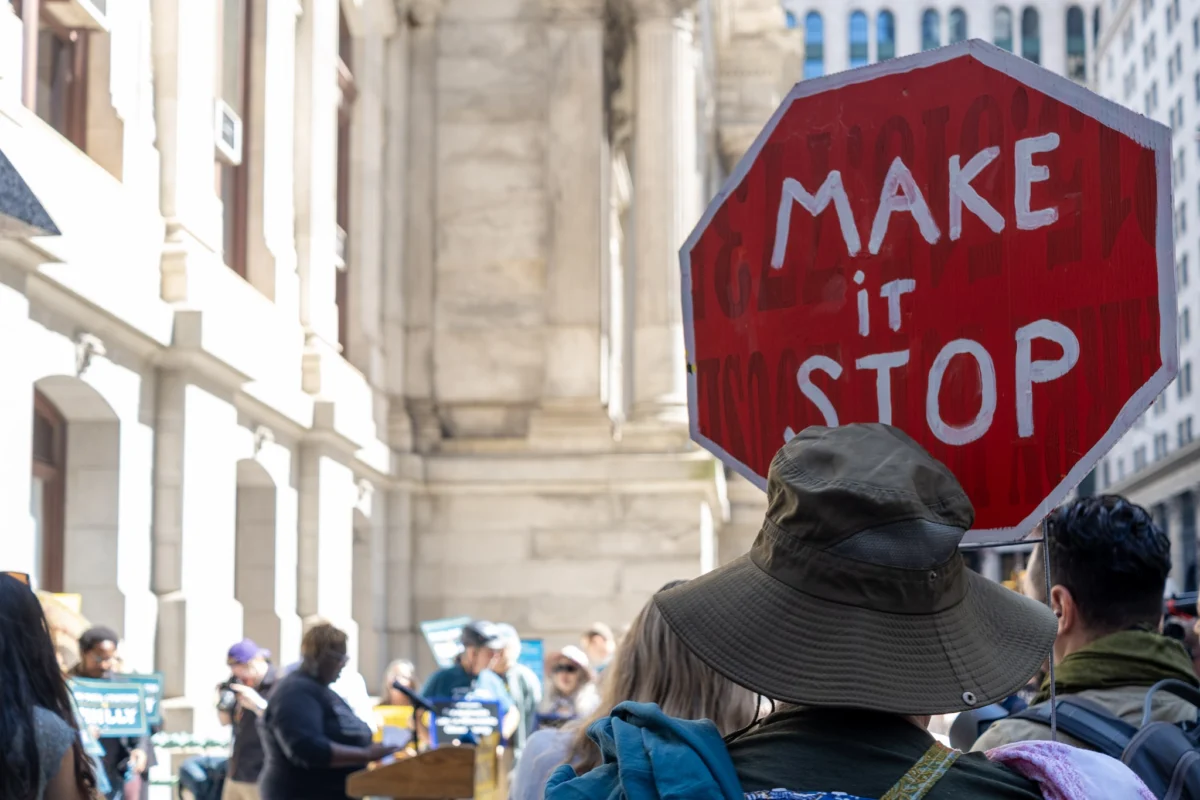
Across the United States, communities are increasingly pushing back against the massive, windowless, energy-intensive warehouses that characterize modern data centers. From rural Virginia to the suburbs of Texas, local governments are grappling with the unintended consequences of rapid infrastructure expansion: strained water supplies, noise pollution, and the aesthetic degradation of landscapes.
Notably, Texas recently halted several new data center projects, with state leadership calling for audits to ensure that the rapid influx of high-demand facilities does not compromise the state’s energy stability. This is not an isolated incident; it represents a broader trend of municipal and state-level skepticism toward infrastructure that consumes vast resources while offering relatively few long-term jobs.
The Power Grid Bottleneck
Even if a developer secures the land and the permits, they face a more fundamental barrier: electricity. The U.S. power grid, particularly in regions dominated by legacy infrastructure, is currently incapable of supporting the aggressive growth targets of AI developers. As noted by experts, the "scramble for electricity" is not merely about finding a power source; it is about securing transmission capacity, upgrading substations, and navigating the often-opaque interconnection queues managed by regional transmission organizations.
Chronology of a Crisis: How We Got Here
The current tension is the result of a rapid collision between exponential demand and linear infrastructure development.
- 2022–2023: The Generative AI Explosion: The release of ChatGPT and the subsequent "AI arms race" led tech giants to scramble for compute power, shifting the industry focus from general-purpose cloud storage to high-density AI-ready clusters.
- Early 2024: The Interconnection Queue Crisis: As data center developers flooded regional power grids with requests for new connections, grid operators were forced to pause or extend wait times significantly, highlighting the inadequacy of existing transmission networks.
- Late 2024–Early 2025: The Rise of "Energy Tech" Investment: Recognizing that power was the primary constraint, tech companies began pivoting from pure data center development to direct investments in energy technology, including modular nuclear reactors and advanced battery storage.
- Mid-2026: The "Reality Check" Phase: As seen in recent regulatory actions in Texas and beyond, the industry is entering a period of consolidation. Financial analysts and industry experts are now distinguishing between "tier-one" projects—those with secured power and broad support—and speculative projects that serve primarily to pump up real estate valuation.
Supporting Data: By the Numbers
To understand the scale of the challenge, one must look at the discrepancy between planned capacity and actual grid capability:
- The Demand-Supply Gap: According to recent projections from energy consultants, the demand for electricity from data centers in the U.S. is expected to grow by nearly 15–20% annually through 2030.
- Permitting Lag: On average, the time required to bring a large-scale data center from initial site selection to full operational status has increased by approximately 18 months since 2020.
- Capital Allocation: While billions of dollars have been pledged to AI infrastructure, data from market observers suggests that nearly 40% of announced projects are currently "stalled" or "under indefinite review" due to the inability to secure definitive energy contracts.
Expert Analysis: The Equity Perspective
On a recent episode of the Equity podcast, hosts Rebecca Bellan and Tim De Chant sat down with Brent Nelson, senior managing director of markets and strategy at Ascend Analytics, to dissect this phenomenon.
Nelson argues that the industry is undergoing a "valuation filter." In the early days of the AI boom, capital flowed indiscriminately into anything labeled "data center." Today, the sophisticated players are focusing on energy-first strategies. "The projects that will survive are the ones where the developer has internalized the energy challenge," Nelson explained. "If you don’t have a plan for where your electrons are coming from, you don’t have a project; you have a wish list."
The discussion highlighted a growing trend: the emergence of "energy-integrated" development. Developers who are partnering with utility providers to build dedicated generation capacity—rather than simply plugging into the existing grid—are the only ones likely to move at the speed required by the AI sector.
Official Responses and Policy Implications
Policymakers are finding themselves in a difficult position. On one hand, they recognize the economic necessity of hosting AI infrastructure to remain competitive globally. On the other, they are under immense pressure from constituents concerned about rising electricity prices and grid instability.
- The Regulatory Shift: We are seeing a move toward more stringent zoning requirements and impact fees. States are beginning to mandate that data center operators contribute to the cost of grid upgrades, effectively ending the era of "free-ride" development.
- The Federal Role: The Department of Energy has increased its focus on the "nexus of AI and energy," seeking to streamline the approval process for transmission lines while simultaneously enforcing stricter efficiency standards for high-performance computing facilities.
The Future: Implications for the AI Economy
The implications of this "Great Filtration" of data centers are profound for the broader tech ecosystem.
1. Market Consolidation
The era of the small, independent data center developer may be drawing to a close. Only the largest tech conglomerates—the "hyperscalers"—and the most well-capitalized private equity firms possess the financial and political leverage to navigate the current regulatory and energy landscape. We should expect a wave of mergers and acquisitions as smaller, stalled projects are absorbed by larger entities capable of solving the "power puzzle."
2. A Shift Toward Decentralization
As primary hubs like Northern Virginia and Silicon Valley reach their physical and electrical limits, we are likely to see a shift toward "secondary" locations. These are regions with abundant, underutilized renewable energy potential, such as parts of the Pacific Northwest or the Midwest, provided that transmission infrastructure can be built out to reach them.
3. The "Energy-Tech" Pivot
The most successful AI companies of the next decade will likely function as much like energy companies as they do software firms. The integration of advanced geothermal, small modular reactors (SMRs), and grid-scale battery storage into data center design will become the standard, not the exception. Companies that fail to innovate on the energy front will find themselves unable to scale, regardless of the quality of their AI models.
Conclusion
The data center boom is not over, but it is certainly entering a more mature, more difficult phase. The days of speculative land-grabbing are fading, replaced by a cold, hard focus on the laws of physics and the realities of the power grid.
For investors and industry participants, the message is clear: look past the press releases. Follow the power contracts, track the grid interconnection progress, and monitor the local permitting environments. The companies and developers that can bridge the gap between AI’s insatiable demand for compute and the world’s finite supply of energy will define the next chapter of the digital age. Those that cannot will simply become part of the infrastructure’s discarded history.
To stay updated on these developments, subscribe to the Equity podcast on YouTube, Apple Podcasts, Overcast, or Spotify. Follow the team on X and Threads at @EquityPod.
About the Author