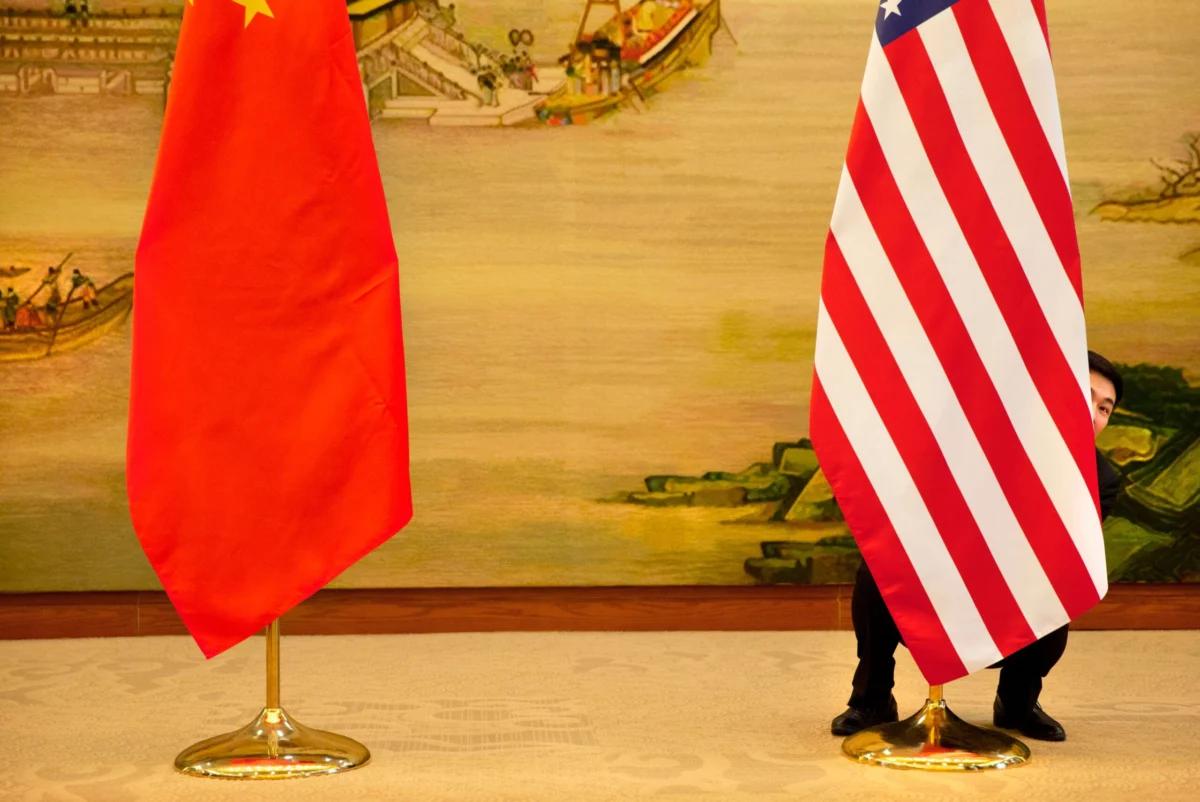
In a decisive move to fortify national security and domestic industrial autonomy, the United States has launched a significant regulatory offensive against foreign-made advanced robotics and unmanned aerial systems (UAS). Throughout July and August, the U.S. government implemented a series of stringent restrictions on advanced robotic hardware and imposed steep tariffs on imported drones and their critical components. These actions, designed to curb dependence on foreign technology in sectors deemed critical to national interest, signal a fundamental shift in the global robotics landscape, moving away from a single, interconnected marketplace toward a more fractured, regionalized reality.
As Washington draws a line in the sand, the global industry faces a profound question: Can protectionist policies truly foster domestic innovation, or will they simply accelerate the bifurcation of the global market, leaving the U.S. to compete in a bubble while Chinese manufacturers continue to dominate on scale, cost, and real-world implementation?
Chronology of Restrictions and Regulatory Expansion
The U.S. government’s recent intervention is the latest phase in a multi-year effort to insulate strategic industries from foreign influence. The foundation for this policy was laid in 2021 with the establishment of the Federal Communications Commission’s (FCC) “Covered List.” Initially intended to safeguard telecommunications infrastructure, the list targeted entities such as Huawei, ZTE, and Hikvision, citing concerns over surveillance and data security.
In the summer of 2026, this regulatory perimeter underwent a significant expansion. By July, the FCC tightened restrictions on advanced robotic systems, essentially categorizing them alongside sensitive telecommunications hardware. Following this, in August, the White House announced a comprehensive tariff regime on imported drones and their sub-components.
The timeline for these economic measures is aggressive:
- July 2026: Initial FCC restrictions on advanced robotic systems are formalized, targeting hardware that could pose security risks.
- August 2026: The White House issues a fact sheet confirming steep tariffs on drones and UAS components, citing national security as the primary driver for "bolstering U.S. supply chains."
- September 2026: Primary drone tariffs take effect, immediately impacting the cost structure of imported unmanned aerial vehicles.
- 2027 (Projected): A second, more expansive wave of tariffs on drone components is slated for implementation, designed to further decouple the U.S. drone supply chain from Chinese reliance.
The Scale Gap: A Clash of Industrial Philosophies
While the U.S. focuses on security, industry analysts point to a staggering disparity in production capability. According to a report by Counterpoint Research, the global humanoid robotics market is currently defined by an overwhelming concentration of manufacturing power in China. In the first half of 2026 alone, global shipments of humanoid robots surged by nearly 300% year-over-year, with Chinese firms responsible for the vast majority of that growth.
The top five manufacturers—AgiBot, Unitree, Galbot, UBTECH, and Leju Robotics—are all Chinese, collectively accounting for 86% of global shipments in H1 2026. This dominance is not merely a product of lower labor costs; it is a result of deep, vertical integration. Chinese manufacturers are increasingly bringing the entire technology stack—from chips and sensors to structural actuators—in-house.
“The United States leads in frontier AI, software, and semiconductor innovation,” notes Ankur Saxena, an investment director at TDK Ventures. “China leads in manufacturing scale, supply-chain depth, and cost.”
This "scale gap" creates a self-reinforcing cycle. By deploying thousands of units across diverse environments, Chinese firms harvest immense quantities of real-world data, which in turn optimizes their AI models and refines hardware durability. This rapid iteration, coupled with lower price points, makes it difficult for U.S. startups to compete on a purely market-driven basis. As Saxena succinctly puts it: “You cannot sanction your way around a cost curve. You can only out-build it.”
The Shift Toward a Fragmented Global Market
The implications of these trade barriers are prompting a re-evaluation of the "global" robotics market. Industry experts suggest that the dream of a unified, borderless market for robotics is being replaced by a tripartite structure: a China-led sphere, a U.S.-led secure sphere, and a middle-ground regional ecosystem.
The Security-First Model
U.S. and allied manufacturers are positioning themselves as the "trusted" providers. In the drone sector, companies like Virginia-based Heven AeroTech are already observing the split. “The industry is effectively splitting into two ecosystems,” says founder and CEO Bentzion Levinson. “A U.S.-led market built around NDAA-compliant systems, and a China-led market focused on low-cost, high-volume production.”
This model relies on the premise that for defense, law enforcement, and critical infrastructure, the premium paid for domestic or allied-nation hardware is justified by the security guarantees provided.
The Cost-Driven Expansion
Chinese firms, finding the U.S. market increasingly hostile, are pivoting toward high-growth, price-sensitive markets. Southeast Asia, Latin America, the Middle East, and parts of Europe are emerging as primary theaters for Chinese expansion. By leveraging the same playbook used by the Chinese electric vehicle industry—scaling at home, exporting, and eventually establishing local production—these robotics companies are poised to capture market share in regions where labor shortages are acute but capital is limited.
The Middle-Ground Contenders
Japan, South Korea, and Taiwan are emerging as potential intermediaries. These nations possess deep institutional knowledge in industrial robotics and precision manufacturing. With giants like Hyundai (owner of Boston Dynamics) and Toyota investing heavily in humanoid and autonomous systems, these players aim to offer a "quality-focused" middle ground. They lack the extreme low-cost advantage of Chinese firms but offer higher levels of reliability and technological pedigree than many early-stage Western startups.
Official Responses and Industry Sentiment
The reception to these regulations has been polarized. Some U.S. industry leaders view the measures as a necessary "preventative strike." Agility Robotics, a U.S.-based developer of the Digit humanoid, publicly welcomed the FCC’s decision. The company argued that proactive regulation prevents foreign-made robots from becoming "deeply embedded" in U.S. infrastructure—a scenario they believe has already played out with consumer drones.
However, there is a countervailing concern among researchers and engineers. Even those who support national security goals express anxiety about the potential for "technological isolationism." If U.S. companies are cut off from global research collaborations or the diverse component ecosystems that have historically kept costs manageable, there is a risk that American robotics could become "gold-plated": highly sophisticated, but too expensive for broad commercial adoption.
Yang Fang, of the California-based agtech firm Beagle Technology, suggests that the future of robotics will be defined by local adaptation. “Robotics is likely to become more regional,” Fang noted. “Machines will be designed for the specific labor needs, regulatory environments, and working conditions of their home markets.”
Implications: The Battle for the Next-Gen Architecture
As the hardware itself becomes a target for tariffs and sanctions, industry observers suggest that the true competitive battleground is shifting. The focus is moving away from the robot chassis toward the underlying "power and payload" architecture.
"The next battleground is over who owns the next-gen energy and payload architecture," says Levinson. As robots and drones become more autonomous and capable of longer missions, the limitations of current battery technology and power management systems are becoming the primary bottleneck. Whoever controls the energy density, high-speed charging, and software-defined payload integration will likely dictate the next era of robotic dominance.
Ultimately, the U.S. strategy of restricting foreign technology is not an end in itself, but a catalyst for a long-term industrial pivot. The success of this policy will not be measured by how many Chinese robots are kept out of the U.S., but by whether the U.S. can mobilize a decade-long investment into a diversified, allied supply chain capable of competing with China’s manufacturing scale. Until that industrial capacity is built, the global robotics industry will remain in a state of flux—a fragmented, competitive, and increasingly geopolitical arena.
About the Author