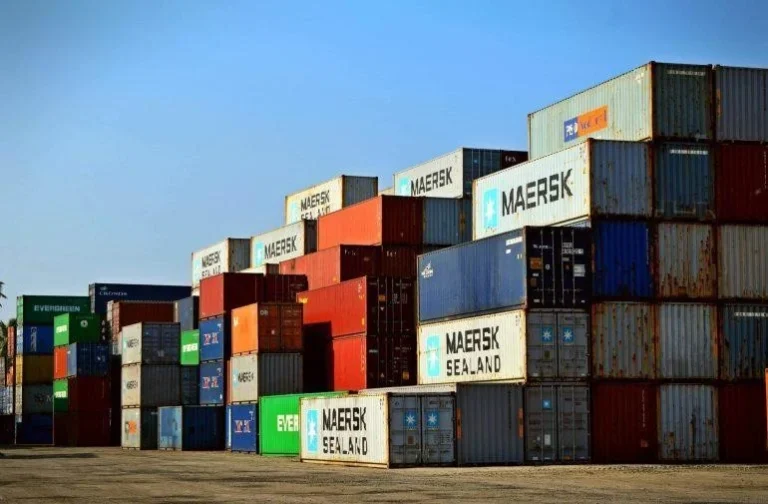
Maritime transport remains the lifeblood of the modern world, functioning as the silent, indispensable engine of global commerce. In 2024, the seas carried a staggering 13 billion tonnes of cargo, facilitating the exchange of energy, food, consumer goods, and raw materials that define our interconnected existence. Within this vast oceanic network, the European Union stands as a titan of logistics, with its ports handling approximately 3.4 billion tonnes—an impressive 26% of the global total.
As global trade faces mounting pressures from geopolitical instability, environmental mandates, and the shift toward digital logistics, the European maritime sector is undergoing a profound transformation. According to the EU Blue Economy Observatory, nearly 90% of the bloc’s external freight trade is conducted via seaborne routes, cementing the strategic importance of port infrastructure to the continent’s long-term economic sovereignty.
The Architecture of Trade: Short Sea vs. Deep Sea
To understand the European maritime landscape, one must distinguish between the two primary operational frameworks: short sea shipping and deep sea shipping.
Short sea shipping is the backbone of regional connectivity. It encompasses the movement of goods within the EU’s internal borders, as well as essential maritime links to candidate countries and EFTA members such as Iceland and Norway. This sector is the vital thread weaving together the Baltic, Mediterranean, and Black Seas, facilitating the rapid movement of goods that keeps the European single market fluid.
Conversely, deep sea shipping involves long-haul, intercontinental voyages that connect Europe to the manufacturing hubs of Asia, the resource-rich markets of the Americas, and the emerging economies of Africa. These routes are the arteries of globalization, subject to the volatility of global events. As noted in recent industry analyses, maritime corridors—most notably the Red Sea—have faced significant disruptions due to security threats, forcing shipping companies to recalibrate routes and reconsider the resilience of global supply chains.
A Statistical Snapshot: Europe’s Port Hierarchy
Data from Eurostat for 2024 highlights a clear hierarchy within the European port network, dominated by a handful of "super-ports" that serve as the primary gateways for the continent’s imports and exports.
The Titans of the North
Rotterdam, located in the Netherlands, remains the undisputed heavyweight champion of European logistics. In 2024, the port processed a colossal 397.3 million tonnes of goods, leveraging its prime position as the entry point for the Rhine-Meuse-Scheldt delta. Following closely is the Antwerp-Bruges complex in Belgium, which handled 243.7 million tonnes, solidifying its status as a critical hub for petrochemicals and consumer goods. Hamburg, Germany’s primary gateway, ranks third with 97 million tonnes.
The gap between the top three and the rest of the pack is substantial, reflecting the immense infrastructure investment required to service the world’s largest container vessels.
The Emerging Powerhouses
Beyond the top three, a highly competitive second tier has emerged. Spain’s Algeciras occupies the fourth spot with 81.5 million tonnes, followed by Amsterdam (78.8 million tonnes) and the French HAROPA network (Le Havre and Rouen), which recorded 76.6 million tonnes. Poland’s Gdansk (71 million tonnes) continues to see significant growth, reflecting the shifting economic center of gravity toward Eastern Europe. Rounding out the top ten are Marseille (66 million tonnes), Valencia (64.5 million tonnes), and the Romanian port of Constanta (57.6 million tonnes), which has become increasingly vital for grain exports from the Black Sea region.
The Secondary Tier: Resilience and Range
The ports ranked 11th to 20th showcase the diversity of the European maritime landscape. This bracket includes major regional players such as Barcelona (55.5 million tonnes), Italy’s Trieste (53.5 million tonnes), and Genova (47.4 million tonnes). Portugal’s Sines, Greece’s Piraeus, and the German hub of Bremerhaven also remain critical, handling between 42 and 44 million tonnes each. The presence of Goteborg (Sweden) and Zeeland (Netherlands) highlights the geographic breadth of the sector’s reach.
Country-Level Performance: A Continental Overview
When the data is aggregated by nation, the Netherlands stands at the pinnacle of the EU, handling 538.1 million tonnes. However, the competition is fierce. Italy ranks second with 488.6 million tonnes, closely followed by Spain with 486 million tonnes. This trio forms the Mediterranean-North Sea corridor that drives much of the continent’s industrial production.
Belgium (274.9 million tonnes), Germany (273.9 million tonnes), and France (269.8 million tonnes) round out the major players, all operating within a narrow band of volume, which underscores the high degree of inter-port competition within the EU.
Significantly, when EU candidate countries are factored into the analysis, the map of European maritime influence expands. Turkey, with a massive throughput of 524.7 million tonnes, would rank as the second busiest nation in the broader European sphere, reflecting its role as a bridge between Europe, Asia, and the Middle East. Norway, with 212.1 million tonnes, also maintains a dominant position, largely driven by the energy and fishing sectors.
Chronology of Challenges and Adaptations
- Early 2024: Global maritime trade faces immediate headwinds as regional conflicts in the Red Sea cause shipping companies to divert vessels, increasing transit times and costs.
- Mid-2024: Eurostat releases the primary data for the first half of the year, confirming that despite regional conflicts, the volume of goods through major EU ports remains robust, highlighting the inherent elasticity of the sector.
- March 2026: The European Commission takes decisive action to secure the future of the sector, announcing a dual-strategy initiative aimed at long-term resilience. This policy package addresses the "triple threat" of sustainability, security, and digital competitiveness.
- Ongoing: Ports across the continent begin integrating AI-driven cargo management and green hydrogen bunkering infrastructure, signaling a move away from fossil-fuel-dependent logistics.
Official Responses and Strategic Policy
The European Commission has long maintained that maritime transport is not merely a utility but a catalyst for European prosperity. Recognizing that the sector is the primary vehicle for the European Green Deal, the Commission’s strategy adopted in March 2026 focuses on decarbonizing the waterborne sector.
The initiative targets three primary pillars:
- Sustainability: Incentivizing the transition to zero-emission vessels and mandating shore-side electricity for ships at berth to reduce urban air pollution in port cities.
- Security and Resilience: Enhancing cybersecurity protocols for port infrastructure and diversifying supply chains to ensure that regional conflicts cannot paralyze the European economy.
- Competitiveness: Streamlining customs procedures through digital "Single Window" systems and promoting the shipbuilding industry to reduce reliance on non-EU manufacturers.
"Our ports are the gateways to our future," a Commission spokesperson stated during the strategy launch. "By investing in the digitalization and greening of our maritime sector, we are ensuring that Europe remains a competitive, secure, and sustainable leader in global trade."
Implications: The Future of Maritime Logistics
The data from 2024 paints a picture of a sector that is remarkably resilient but facing an inflection point. The concentration of volume in a few mega-ports like Rotterdam and Antwerp-Bruges presents both an opportunity and a risk. While these ports achieve unparalleled economies of scale, their size makes them single points of failure in the event of industrial action, climate-related disruptions, or cyberattacks.
Furthermore, the rise of ports like Gdansk and Constanta signals a strategic pivot. As Europe seeks to move away from over-reliance on traditional Atlantic trade routes, the Baltic and Black Sea ports are likely to see increased investment.
Ultimately, the European maritime sector is moving toward a model where efficiency is measured not just in tonnes, but in "carbon-per-tonne" and "resilience-per-voyage." As the world navigates a period of profound geopolitical flux, the stability of Europe’s maritime supply chain will remain the primary metric of the bloc’s economic health. The transition toward greener, more secure, and more technologically advanced ports will determine whether Europe remains the central node in the global trade network for the decades to come.
With 13 billion tonnes of goods currently in motion across the globe, the European Union has made its intent clear: it will not only participate in global trade—it will define the standards by which that trade is conducted.
About the Author