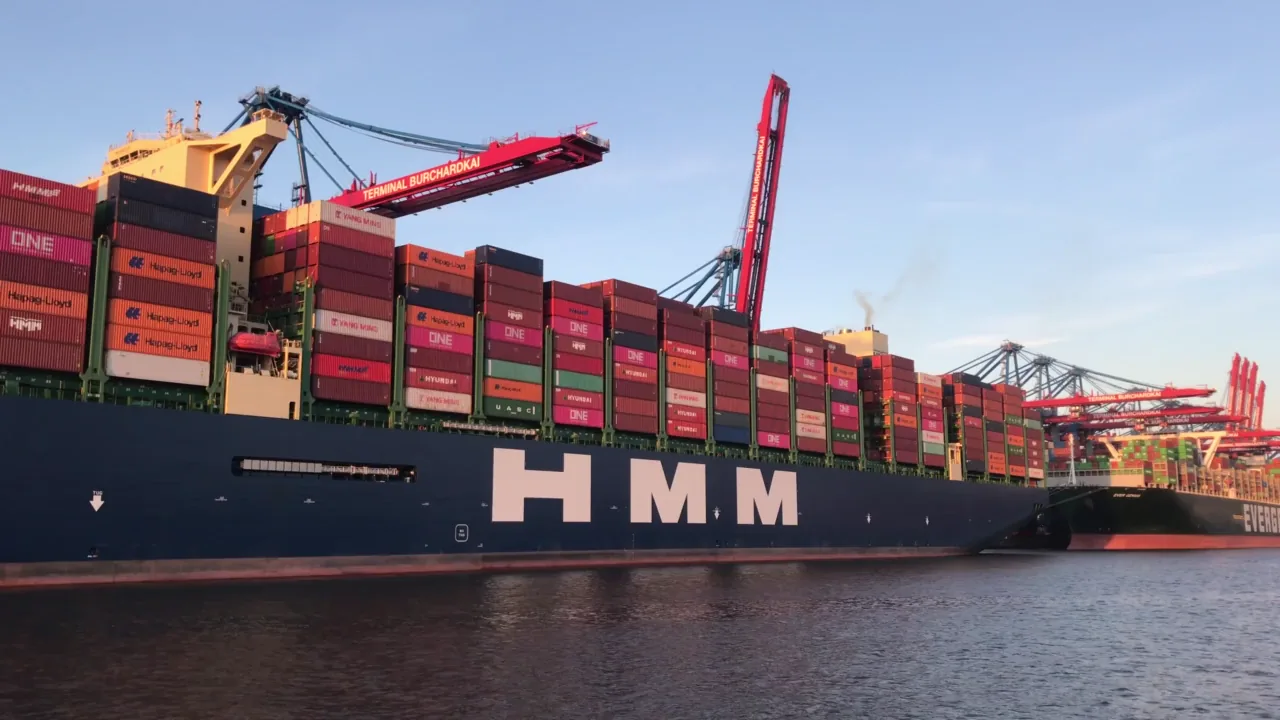
The global maritime logistics sector is currently navigating its most volatile period since the peak of the COVID-19 pandemic. According to the latest Xeneta Weekly Ocean Container Shipping Market Update, spot freight rates on primary trade lanes connecting the Far East to the United States have experienced a staggering vertical ascent. Triggered by the recent escalation of the crisis in the Strait of Hormuz, the cost of moving goods across the Pacific has skyrocketed, with rates on both the US West Coast (USWC) and US East Coast (USEC) routes surging by 324% and 325%, respectively, since the end of February 2026.
This extraordinary spike has reignited concerns regarding global supply chain resilience, inflation, and the vulnerability of critical maritime chokepoints. As Peter Sand, Chief Analyst at Xeneta, points out, the industry is no longer dealing with localized disruption; it is grappling with a fundamental reordering of freight economics driven by geopolitical volatility.
The Anatomy of the Surge: Main Facts and Data
The current economic climate for ocean freight is defined by the rapid convergence of high demand and supply-side constraints. The 325% increase in rates is not merely a statistical anomaly but a reflection of the market’s extreme sensitivity to the Middle Eastern theater of conflict.
The Proximity to Historic Highs
Perhaps most alarming to industry observers is how close current rates have climbed toward the "COVID-era" records. During the pandemic, supply chains buckled under unprecedented demand for consumer goods, leading to astronomical freight costs. Today, the trade lane to the US West Coast sits a mere 18% below those all-time highs, while the US East Coast route is trailing by only 11%.
The Fuel Factor
Beyond the baseline container rates, secondary costs are exerting significant upward pressure. Rising bunker fuel prices, exacerbated by the geopolitical instability in the Middle East, have forced carriers to implement aggressive fuel surcharges. These surcharges are effectively "stacking" on top of the spot rate increases, creating a compounding effect that significantly erodes the profit margins of retailers and manufacturers who rely on just-in-time inventory.
Chronology of the Crisis
To understand the current state of the market, one must look back at the precipitating events that shifted the landscape from a period of relative stability to the current "hot" market.
- Late February 2026: Before the onset of the Hormuz crisis, the container market was operating under a "new normal." Rates were stable, and carriers were managing capacity in a post-pandemic lull.
- Early March 2026: The intensification of tensions in the Strait of Hormuz—a vital artery for global energy and a key indicator for maritime security—sent shockwaves through the shipping industry. Insurance premiums for vessels traversing the region spiked, and carrier routes were rerouted to avoid potential conflict zones.
- Q2 2026: As the geopolitical situation hardened, the impact on shipping schedules became undeniable. Carriers began absorbing the costs of longer transit times and higher operational expenditures, passing these directly to shippers via spot rate hikes.
- August–September 2026: The market entered a phase of peak intensity. Carriers, recognizing the profitability of the current climate, began aggressively managing capacity.
- Present Day: The market is bracing for the "Golden Week" push, a period where shippers typically rush to move goods out of Asia before the week-long holiday shutdown, which is expected to provide one final, short-term catalyst for rate growth.
Carriers’ Strategic Response: Capacity Management
In response to the surge, major ocean carriers have been quick to capitalize on the heightened demand. The Xeneta update highlights a tactical shift in capacity allocation, particularly toward the US East Coast.
Increased Capacity for High-Yield Routes
Data indicates that carriers have increased offered capacity on the Far East to US East Coast route by 6–7% in September compared to August. This move is a classic hedge: carriers are deploying more tonnage to high-yield lanes to maximize revenue while the market remains "hot."
However, this strategy is not without risks. Analysts suggest that this capacity influx is a short-term reaction to current rate levels. Should demand soften unexpectedly or geopolitical tensions subside, the excess capacity could lead to a rapid correction in rates within the next two to three weeks.
Implications for Global Trade and Economy
The Sensitivity of Maritime Chokepoints
The current situation serves as a grim reminder of how dependent the global economy is on stable, open waterways. The Strait of Hormuz, while primarily associated with oil, is a vital conduit for the global supply chain. When geopolitical friction hits these points, the ripple effects are felt instantly in the retail sector, manufacturing, and consumer pricing.
The mere possibility that the pandemic-era rate records could be broken—a prospect Peter Sand describes as an "extraordinary market development"—has triggered a sense of urgency in boardroom discussions across the globe. Companies are being forced to re-evaluate their reliance on transpacific logistics, with many considering "near-shoring" or "friend-shoring" strategies to mitigate future risks.
The "Golden Week" Effect
The industry is currently looking toward the start of October with bated breath. The upcoming Golden Week in China, which traditionally sees a factory-wide pause, is expected to act as a final "sprint" for cargo throughput. Shippers are currently front-loading inventory to ensure they are not caught out by the anticipated rate volatility and potential port congestion that often follows such spikes.
Once the Golden Week concludes, the consensus among analysts is that the frenetic pace of growth will begin to soften. Whether this represents a stabilization of the market or a "cooling off" period before further volatility remains to be seen.
Expert Commentary: Is a Record-Breaking Peak Inevitable?
While the current rates are already historically high, the question of whether they will surpass the pandemic-era peak remains the subject of intense debate. Xeneta’s analysis suggests that if a new record is to be set, it will almost certainly occur on the US East Coast trade.
The vulnerability of the USEC route is tied to its longer transit times and the increased risk profile associated with vessels entering the Atlantic via routes that may be impacted by the wider geopolitical ripple effects.
Long-term Economic Considerations
The economic implications of this surge extend far beyond the shipping industry. Higher freight costs are essentially a tax on global trade. For the consumer, this often translates into higher prices for electronics, apparel, and home goods. For the manufacturer, it complicates the cost-benefit analysis of globalized production.
As Peter Sand noted, the discussion regarding these records is a barometer for the health of global trade. The fact that the industry is even entertaining the possibility of eclipsing COVID-era highs highlights a systemic fragility that policymakers and corporate leaders are struggling to address.
Future Outlook: A Market in Transition
As we move into the final quarter of 2026, the maritime logistics industry remains at a crossroads. The following factors will likely determine the trajectory of the market:
- Geopolitical De-escalation: Any sign of stabilization in the Middle East would likely lead to an immediate, though perhaps gradual, easing of freight rates.
- Carrier Discipline: If carriers maintain their current capacity management strategies, rates may remain elevated even if demand begins to wane.
- Consumer Sentiment: The ultimate driver of these freight rates remains consumer demand. If the US economy shows signs of slowing, the "hot" market will naturally cool, regardless of geopolitical pressures.
In conclusion, the shipping industry is currently in the grip of a perfect storm. The confluence of geopolitical instability, tactical capacity management by carriers, and the seasonal rush of Golden Week has created a market environment characterized by high stakes and historic price points. For stakeholders in the global supply chain, the coming weeks will be a test of resilience, adaptation, and strategic foresight as they navigate a landscape that continues to challenge the definitions of "normal."
Whether the industry avoids the record-breaking peaks of the pandemic or enters a new, more volatile era of maritime trade, one thing is certain: the events of 2026 have irrevocably changed the way the world views the security and cost of ocean container shipping.
About the Author