As the autumn leaves settle and the supply chain industry shifts its collective focus toward the high-stakes theater of the peak shipping season, a familiar but intensified tension hangs in the air. For logistics professionals, the coming weeks represent the ultimate stress test—a trial by fire to determine if the strategic investments and operational refinements made over the preceding months are sufficient to withstand the seasonal surge.
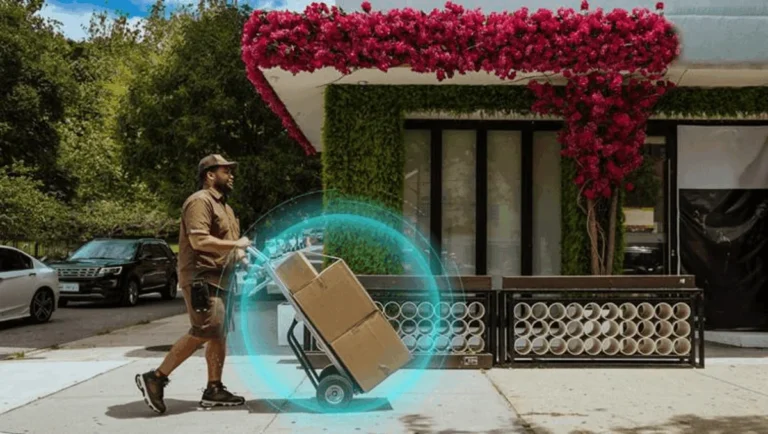
While warehousing and long-haul logistics have faced their own hurdles, the most critical pressure point remains the “final mile.” This final leg of the journey—the transition of goods from distribution hubs to the doorsteps of consumers—has evolved into the most complex, costly, and scrutinized segment of the modern logistics landscape. As e-commerce volumes continue to climb and consumer expectations for near-instantaneous delivery solidify, the industry finds itself grappling with a multifaceted crisis of profitability, regulatory compliance, and technological integration.
The Cost of Complexity: A Financial Deep Dive
Last-mile delivery is widely acknowledged as the most expensive component of the supply chain. Industry analysts estimate that this final, critical segment can account for upwards of 40% of total delivery costs. This figure is not merely a static overhead; it is a dynamic, shifting burden that has been aggravated by a decade of relentless e-commerce growth.
The "Amazon effect"—the standard set by retail giants for same-day and next-day delivery—has forced carriers and shippers to optimize for speed at the expense of efficiency. However, the current economic climate is proving that this model is increasingly unsustainable without fundamental operational changes.
According to the latest industry data, shippers and carriers are finding that last-mile delivery costs are systematically outpacing revenues. The culprits are well-documented: volatile fuel prices and a chronic, high-stakes labor shortage that spans both warehousing and the driving workforce. When these macroeconomic factors collide with the localized intensity of peak-season demand, the result is a margin-crushing environment that leaves little room for error.
The 2026 Snapshot: Insights from the Frontlines
To understand the gravity of these challenges, one must look to the "Eye on the Last Mile America 2026" report, a comprehensive study conducted by the logistics platform FarEye. Surveying over 500 delivery operators nationwide, the report paints a stark picture of an industry under siege.
The data reveals that 70% of last-mile operators identify fuel costs as one of their primary financial pressures. Simultaneously, over 50% of respondents cite ongoing labor issues as a significant inhibitor to growth and profitability. These are not merely operational nuisances; they are systemic challenges that dictate the survival of smaller carriers and the profitability of major shippers.
The report highlights that the traditional strategies for managing these costs—such as fuel surcharges and aggressive workforce recruitment—are no longer providing the relief they once did. Instead, the industry is reaching a point of diminishing returns, where the cost of finding, training, and retaining reliable, compliant drivers is becoming as significant a factor as the fuel that powers their vehicles.
Regulatory Realities: The Compliance Conundrum
Beyond the balance sheet, a new layer of risk has been introduced via the legal system. The May 2026 Supreme Court ruling in Montgomery v. Caribe Transport II LLC has sent shockwaves through the logistics sector, fundamentally altering the liability landscape for freight brokers and shippers.
The ruling clarified that freight brokers can be held legally liable under various state laws for accidents involving the federally licensed motor carriers they hire. This decision has profound implications for the "unvetted" segment of the market. Shippers who have historically prioritized low rates by utilizing substandard brokers or unverified carriers are now finding that the cost of such savings may be legal liability.
Gaurav Srivastava, co-founder and Chief Product and Technology Officer at FarEye, emphasizes that this ruling has shifted the priority from "lowest cost" to "highest compliance."
“Companies are now scrambling to find and vet drivers more rigorously,” Srivastava explains. “While the added costs associated with hiring certified, insured, and compliant operators are justified—they are the price of doing business in a safer, more regulated environment—the transition is creating immense pressure on our customers. The margin for error regarding driver quality and insurance documentation has effectively vanished.”
This shift toward heightened compliance acts as an additional tax on the already strained last-mile delivery budget. Shippers are finding that they must now invest in verification technologies and higher-tier carrier contracts, further squeezing the profit margins that were already under threat from fuel and labor inflation.
The AI Revolution: Operational Control in an Uncontrollable Market
If the industry cannot control the price of diesel or the global labor market, where can it exert influence? The answer, according to current industry trends, lies in the granular control of operational processes through advanced technology.
The 2026 data shows a massive pivot toward Artificial Intelligence (AI) as the primary tool for mitigating these rising costs. According to FarEye’s research, the implementation of AI products among last-mile operators jumped from 46% in 2025 to over 66% in 2026. Perhaps more telling is the rise in "extensive operational adoption," which surged from a mere 4% to nearly 14% in just one year.
Key AI Use Cases in Logistics:
- Estimated Time of Arrival (ETA) Prediction (39%): Precision in delivery windows is no longer a luxury; it is a necessity for reducing failed delivery attempts and customer support overhead.
- Demand Forecasting (36%): By predicting spikes in volume with higher accuracy, companies can optimize their fleet deployment and staffing levels before the peak season hits.
- Customer Support (31%): AI-driven chatbots and automated tracking systems are significantly reducing the burden on human support staff, allowing them to focus on complex delivery exceptions.
- Real-Time Dynamic Routing (21%): This is perhaps the most critical tool for fuel savings. By constantly recalculating routes based on traffic, weather, and delivery density, operators are cutting down on unnecessary mileage and idling time.
The Strategic Shift: Agentic AI
The current frontier of this technological adoption is "agentic AI." Unlike traditional AI, which typically provides insights that a human must then act upon, agentic AI is designed to autonomously initiate and execute processes.
For a logistics manager, this means the software doesn’t just suggest a route; it dynamically updates the delivery manifest in real-time, negotiates capacity constraints with third-party partners, and automatically alerts the customer to changes in arrival times. As Srivastava notes, this is the ultimate hedge against external volatility.
"We cannot dictate the price of oil or the availability of labor," Srivastava says. "But we can control the efficiency of every delivery. We can control how much fuel a vehicle consumes by optimizing its path, and we can maximize the capacity of every truck on the road. That is where the battle for profitability is currently being won."
Implications: Preparing for the Future
As we head into the peak season of 2026, the contrast between "prepared" and "unprepared" operations will be laid bare. The supply chains that have integrated AI-driven decision-making tools into their core workflows are likely to see a significant performance advantage.
For those lagging behind, the implications are severe. The combination of legal liability, rising fuel costs, and the inability to effectively forecast demand creates a "scissors effect" that can quickly erode a year’s worth of profit.
However, the rapid adoption of AI suggests that the industry is not sitting idle. There is a palpable shift toward a more data-driven, compliant, and efficient logistics model. The goal is no longer just to get a package from A to B; the goal is to do so with the highest level of transparency, the lowest carbon footprint, and the most efficient use of resources.
As the peak season reaches its crescendo, the companies that thrive will be those that have successfully transformed their last-mile operations from a cost center into a strategic asset. By leveraging technology to navigate the regulatory and economic headwinds, these organizations are not just surviving the current crisis—they are building the infrastructure for the next generation of global commerce.
In the final analysis, the 2026 peak season will be remembered as the moment the logistics industry fully embraced the digital transformation. The tools are available, the mandate for compliance is clear, and the financial imperative has never been higher. The question is no longer whether the industry can handle the pressure, but how quickly it can scale these solutions to meet the demands of an ever-accelerating market.
About the Author